
 Skip to content
Vineyard financing, cotton farm financing, agribusiness expansion financing, equipment shed financing, and seed financing provide agricultural producers with the capital needed to purchase land, grow specialty crops, expand operations, construct storage facilities, and invest in quality planting materials.
These financing solutions help farmers improve productivity, strengthen cash flow, modernize their businesses, and build sustainable agricultural operations that are positioned for long-term growth and profitability.
Agribusiness loans are designed to support farmers, producers, and agricultural businesses with the capital needed to operate, expand, and improve productivity. Whether you are managing seasonal cash flow, purchasing land, upgrading machinery, or investing in livestock, our financing solutions are structured to match the unique cycles of agriculture.
We understand that farming is not a fixed-income business. That’s why our lending approach focuses on flexibility, seasonal repayment options, and long-term financial stability for agribusiness operators.
Long-term financing for major investments like land, infrastructure, and expansion projects.
Flexible access to funds whenever your business needs working capital.
Designed to support farming cycles, covering input costs before harvest revenue arrives.
Purchase new or used agricultural machinery with structured repayment plans.
Funding for buying, breeding, and expanding livestock operations.
Industry-focused agricultural financing experts
Flexible repayment plans aligned with crop cycles
Competitive interest rate structures
Fast approval and simple application process
Funding for both small farms and large agribusiness operations
Personalized financial support and advisory
Improve farm productivity and efficiency
Expand agricultural operations and land ownership
Maintain stable cash flow during off-season periods
Invest in modern technology and equipment
Strengthen long-term business growth
Reduce financial pressure during seasonal cycles
Farmers and agricultural landowners
Agribusiness companies of all sizes
Livestock and dairy operators
Agricultural processors and suppliers
Rural business owners involved in food
Affiliate Disclosure: We are an affiliate marketing website and may receive compensation from lending partners. We are not a lender, do not make credit decisions, and do not guarantee approval. Loan terms and rates are determined by individual lenders.
They can be used for land purchase, equipment, livestock, farm expansion, and working capital.
Yes, repayment structures can be aligned with agricultural income cycles.
Approval time depends on documentation, but flexible fast-track options are available.
Yes, both small and large agribusinesses are eligible.
Agricultural businesses often need several types of capital at the same time. A specialty crop operation may require years of investment before reaching full production, while a row-crop business can face substantial planting expenses every season. Growing farms may also need buildings, machinery, land improvements, employees, storage, and additional working capital.
The most effective approach is usually to separate short-term operating requirements from long-term capital investments. Seed and other crop inputs generally turn over during a production cycle, while buildings and permanent improvements can serve an operation for decades. Expansion projects may combine both categories and therefore require more detailed planning.
Farmers can improve financial decisions by building realistic cash-flow projections, understanding the total installed cost of each project, maintaining adequate reserves, and comparing financing structures according to useful asset life rather than simply choosing the lowest payment.
The following nine sections examine specialty agriculture, row crops, growth projects, equipment buildings, crop inputs, underwriting, government programs, and long-term financial planning.
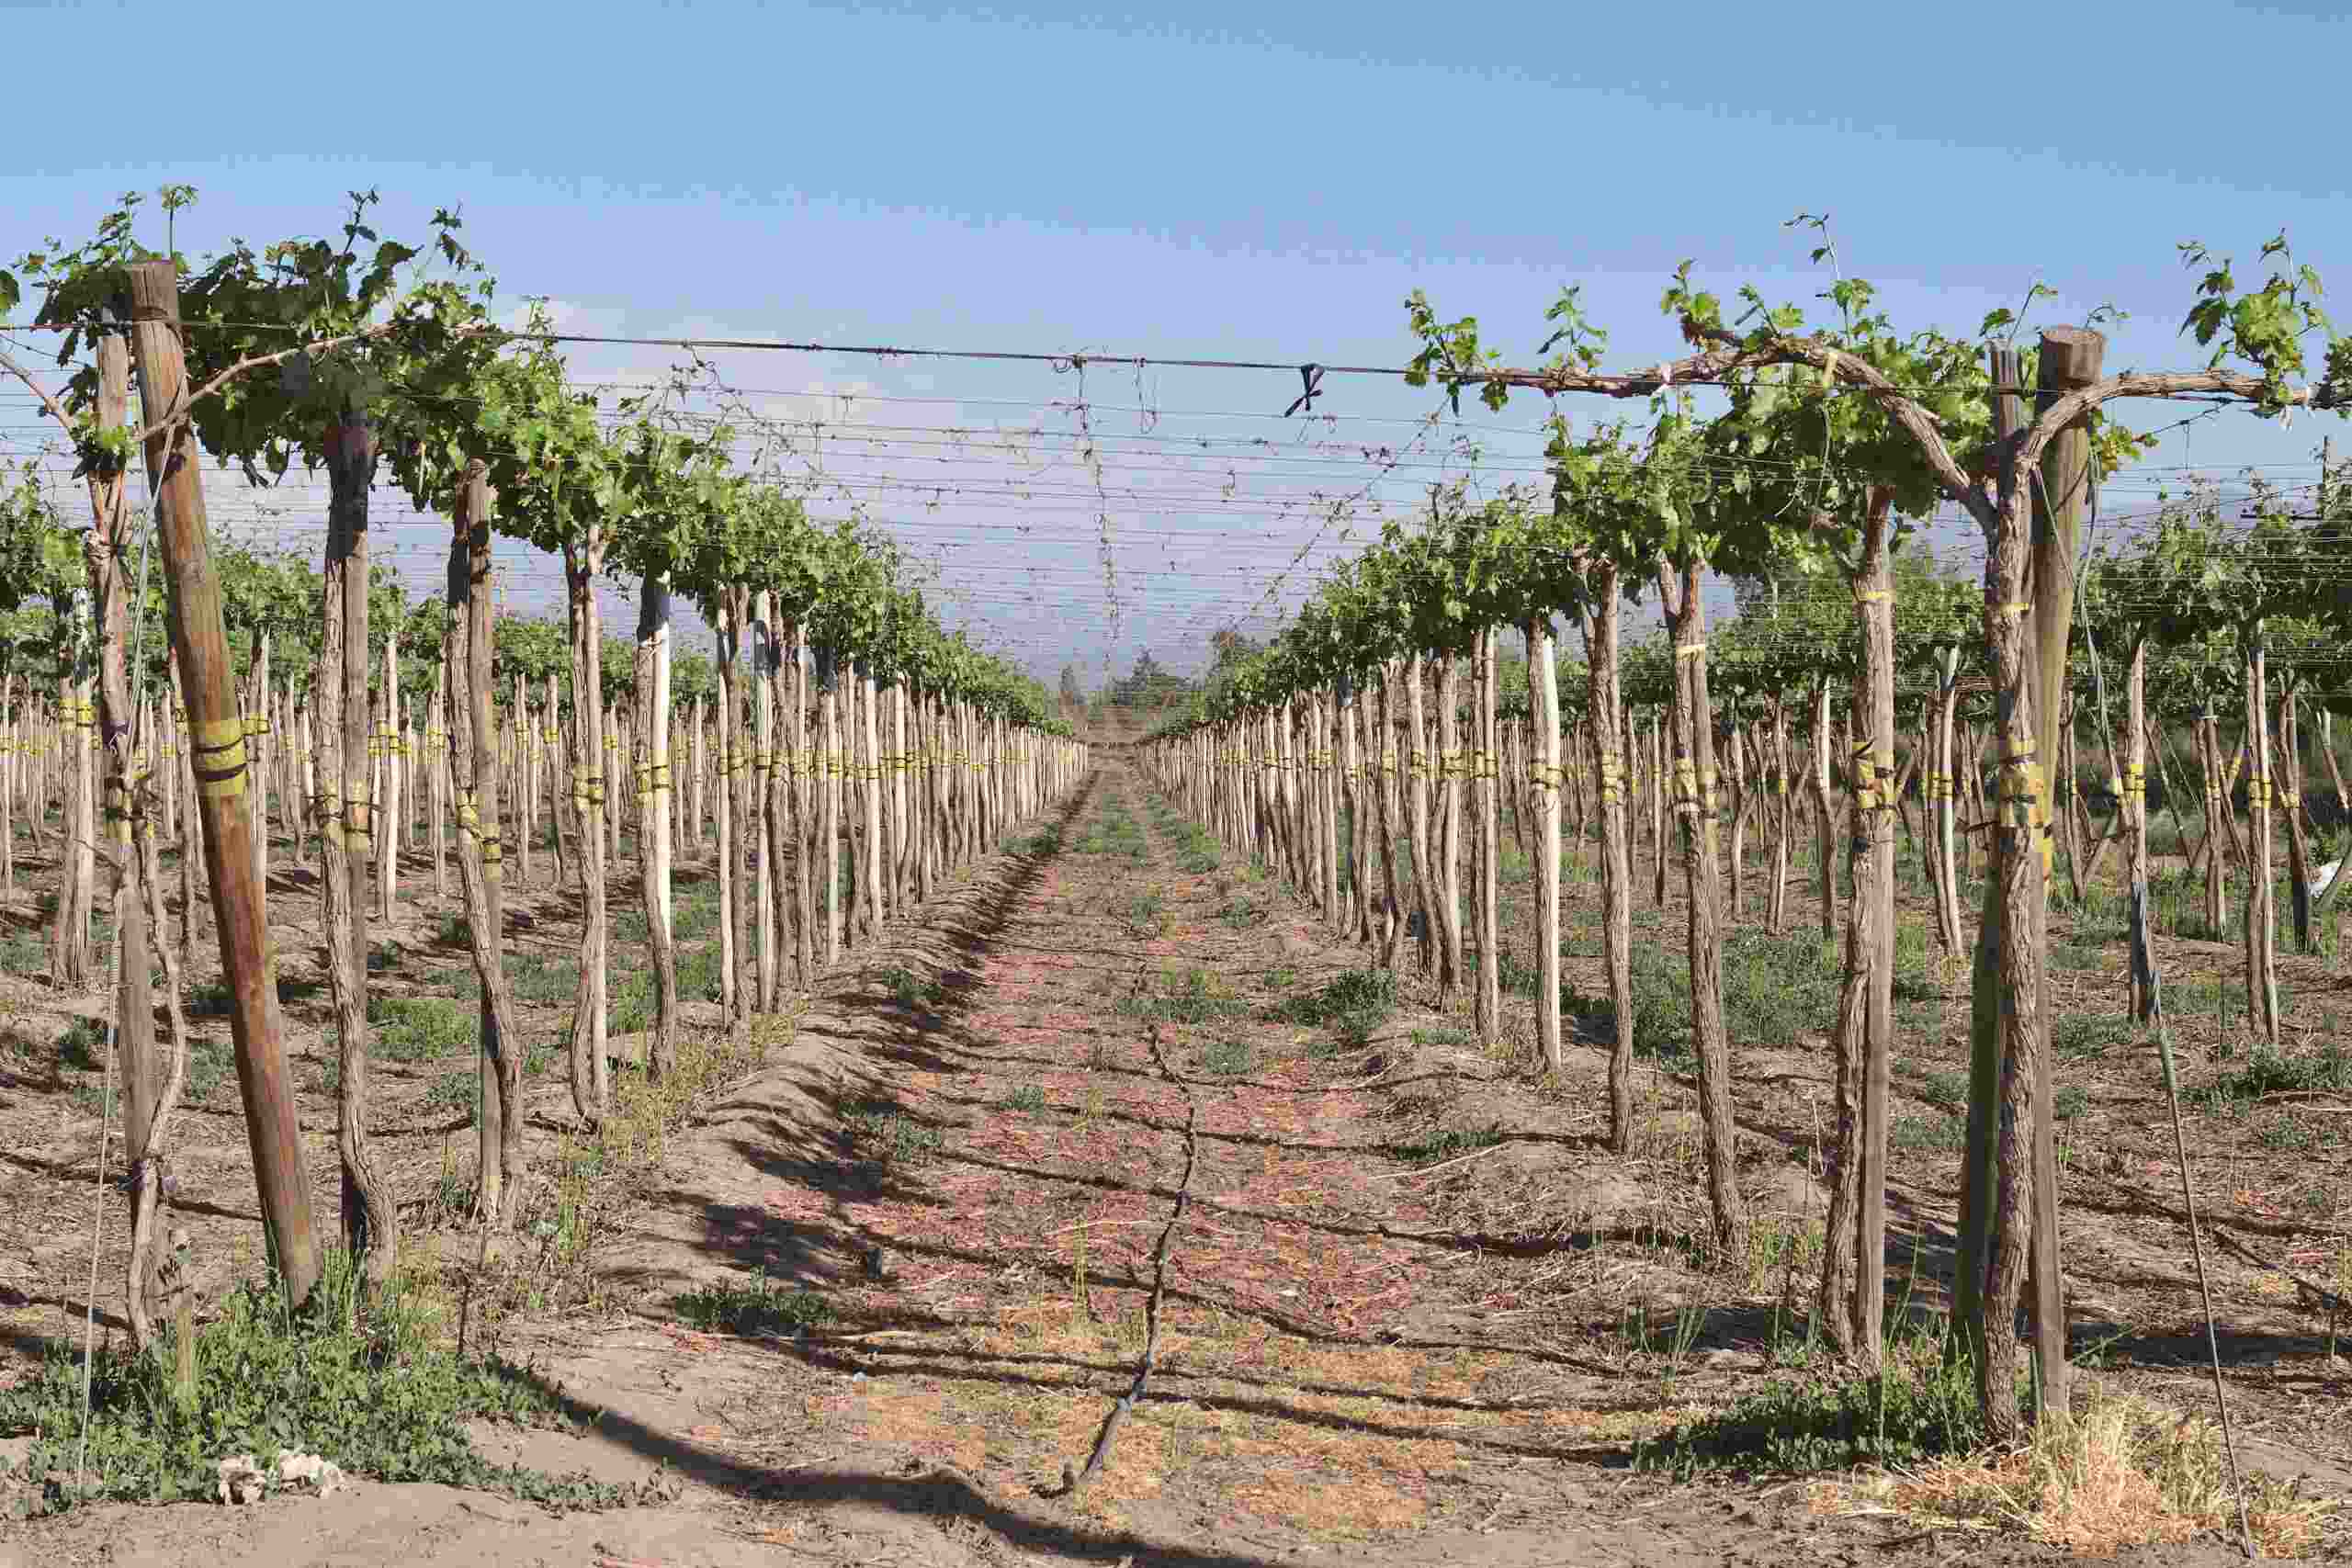
Farmers researching Vineyard financing should budget for land preparation, vines, trellising, irrigation, equipment, labor, crop protection, utilities, storage, and the years that may pass before new plantings reach mature production.
Operations considering cotton farm financing should calculate expected expenses for seed, fertilizer, crop protection, fuel, labor, irrigation where needed, harvesting, transportation, and equipment operation.
Businesses seeking agribusiness expansion financing should create a complete use-of-funds schedule separating property, construction, machinery, technology, livestock or crops, and working-capital requirements.
Applicants exploring equipment shed financing should determine the required dimensions, door clearances, site preparation, electrical service, concrete, ventilation, security, and future machinery-storage needs.
Producers evaluating seed drill financing should estimate acreage, varieties, seeding rates, anticipated prices, replanting risk, and other planting expenses before determining the amount of seasonal capital required.
For additional educational information about agricultural funding, visit AgribusinessLoans.com.
Businesses seeking Vineyard financing should recognize that vineyard development can require significant upfront investment while commercial production may develop gradually over multiple growing seasons.
Producers using cotton farm financing face a different cash-flow cycle because planting expenses generally occur before harvest revenue, creating a strong need for careful seasonal budgeting.
Applicants evaluating agribusiness expansion financing should determine whether growth will immediately increase revenue or whether the project requires a multi-year ramp-up period.
Farmers considering equipment shed financing can include storage requirements in broader property plans so tractors, sprayers, mowers, implements, and maintenance equipment are adequately protected.
Operations using seed financing should avoid underestimating the possibility of additional planting costs caused by poor emergence, weather events, or other production problems.
Vineyards require particularly long-term thinking. Site suitability, soils, climate, water, drainage, plant material, trellis design, disease pressure, labor availability, and market strategy can all influence financial performance.
Applicants using Vineyard financing should maintain separate enterprise budgets when the farm also produces annual crops because permanent plantings and seasonal field production have very different financial characteristics.
Farmers considering cotton farm financing should include harvesting expenses, ginning-related costs where applicable, transportation, equipment repairs, insurance, and interest in addition to basic crop inputs.
Businesses pursuing agribusiness expansion financing for additional acreage should calculate how growth will affect machinery capacity, labor, storage, transportation, insurance, and operating expenses.
Operations exploring equipment shed financing should consider whether larger machinery associated with expansion will require taller doors, wider clear spans, more floor space, or reinforced surfaces.
Producers seeking seed financing should compare expected planting expenses with realistic yield and price assumptions rather than relying exclusively on an unusually profitable previous season.
Farmers utilizing Vineyard financing for new acreage may benefit from phasing development so planting, irrigation, trellising, machinery, and labor requirements do not all create maximum cash demands simultaneously.
Businesses carrying cotton farm financing should stress-test expansion plans against higher input costs, weaker yields, lower prices, or additional equipment repairs.
Operations researching agribusiness expansion financing should define measurable reasons for growth, such as additional productive acreage, increased processing capacity, improved storage, greater livestock capacity, or entry into a new market.
Applicants pursuing equipment shed financing should evaluate both current machinery and equipment expected to be acquired over the next several years before finalizing building dimensions.
Farmers considering seed financing as acreage grows should update seasonal forecasts because planting costs can rise significantly before additional crop revenue is realized.
Growth should be paced according to financial capacity. An operation can be profitable overall yet still encounter stress if several new debt obligations begin at the same time.
Businesses researching Vineyard financing should compare rates, fees, repayment periods, collateral requirements, required contributions, and whether repayment expectations reflect the development period of the operation.
Applicants evaluating cotton farm financing should consider whether scheduled repayments correspond reasonably with the timing of crop revenue.
Farmers considering agribusiness expansion financing should calculate total financing costs rather than selecting a structure simply because it offers a lower initial payment.
Operations seeking equipment shed financing should use the complete installed construction cost, including site work and utilities, when estimating payments.
Producers evaluating seed financing should understand interest calculation, fees, maturity dates, collateral provisions, and repayment expectations before borrowing for planting expenses.
Consider a hypothetical $550,000 agricultural capital project amortized over 15 years:
| Illustrative Rate | Approx. Monthly Payment | Approx. Total Repaid |
|---|---|---|
| 5% | $4,349 | $782,820 |
| 6% | $4,641 | $835,380 |
| 7% | $4,943 | $889,740 |
| 8% | $5,256 | $946,080 |
| 9% | $5,578 | $1,004,040 |
Approximate Monthly Payment

$5,600 |                              █
$5,400 |                              █
$5,200 |                       █      █
$5,000 |                █      █      █
$4,800 |                █      █      █
$4,600 |         █      █      █      █
$4,400 |  █      █      █      █      █
       +-----------------------------------
          5%     6%     7%     8%     9%
These figures are hypothetical educational calculations only. They are not current agricultural rates, lender quotes, market averages, guaranteed terms, or promises of approval.
Operations carrying Vineyard financing may need machinery storage for tractors, sprayers, mowers, cultivation equipment, harvest equipment, and maintenance supplies.
Farmers using cotton farm financing should evaluate whether inadequate machinery storage is contributing to weather exposure, maintenance problems, inefficient organization, or security concerns.
Businesses considering agribusiness expansion financing can incorporate buildings into a broader capital plan rather than constructing new facilities without considering future acreage and machinery needs.
Applicants seeking equipment shed financing should obtain detailed contractor estimates that identify building materials, foundation requirements, electrical work, site preparation, doors, drainage, ventilation, and installation.
Producers carrying seed financing should preserve enough liquidity for planting even when a major building project is underway.
Building size should be based on practical requirements. Excess capacity can unnecessarily increase construction debt, while a structure that is too small may require costly additions shortly after completion.
Eligible producers researching Vineyard financing can investigate Farm Service Agency ownership and operating programs when proposed uses meet applicable requirements.
Farmers seeking cotton farm financing can review FSA operating programs to determine whether qualifying crop-production expenses may be eligible.
Operations considering agribusiness expansion financing should examine both direct and guaranteed agricultural programs along with conventional financing sources.
Applicants evaluating equipment shed financing should verify whether the proposed agricultural structure qualifies under a particular program before depending on government assistance in the project budget.
Businesses seeking seed financing can review operating programs that may support qualifying planting expenses for eligible producers.
Government assistance is not automatic. Eligibility, permitted uses, available amounts, collateral, repayment terms, and application requirements should be confirmed with the appropriate agency.
Applicants seeking Vineyard financing should prepare requested property information, development budgets, planting plans, production assumptions, financial statements, and cash-flow projections.
Farmers applying for cotton farm financing should organize acreage information, crop budgets, equipment schedules, production history where available, existing debt, and expected repayment sources.
Businesses pursuing agribusiness expansion financing should explain how requested capital will be used and provide realistic projections showing the financial effect of expansion.
Operations applying for equipment shed financing should provide contractor proposals, building specifications, site information, construction budgets, and documentation requested by the financing provider.
Producers requesting seed financing should prepare planting budgets showing acres, crop varieties, expected input requirements, and the anticipated production cycle.
Liquidity should remain available after major investments. A farm may own valuable land, crops, buildings, and equipment while still struggling if it lacks enough cash for payroll, fuel, repairs, fertilizer, crop protection, utilities, and other recurring expenses.
Businesses completing projects through Vineyard financing should compare actual establishment costs, labor, yields, operating expenses, and sales with the projections used when planning the development.
Operations repaying cotton farm financing should review actual input costs, yields, harvesting expenses, equipment repairs, and crop revenue after every season.
Farmers carrying agribusiness expansion financing should monitor whether growth is producing the additional revenue, efficiency, or productive capacity anticipated in the original plan.
Businesses using equipment shed financing should track building utilization, maintenance, insurance, energy expenses, and whether the facility continues to meet machinery-storage requirements.
Producers utilizing seed financing should compare actual planting costs and crop performance with the original production budget to improve future capital planning.
A multi-year strategy can coordinate land acquisition, vineyard establishment, crop production, buildings, tractors, harvesting equipment, irrigation, storage, transportation, and operating capital. Instead of attempting every improvement simultaneously, management can prioritize projects according to expected value and available repayment capacity.
Farmers can also find educational agricultural funding information through AgribusinessLoans.com.
Agricultural well financing works best when the repayment structure reflects the nature of the investment. Permanent crops, seasonal field production, buildings, expansion projects, and annual crop inputs each have different financial characteristics.
Vineyards illustrate the importance of long-term planning. Establishing productive acreage can require land preparation, vines, trellising, irrigation, labor, equipment, and ongoing crop management before mature production is achieved.
That development period should be incorporated into realistic financial projections. Producers should avoid assuming that newly planted acreage immediately produces the same revenue as established acreage.
Site selection can also have long-term financial consequences. Soil characteristics, drainage, water availability, climate, disease pressure, topography, and access can influence both establishment costs and ongoing productivity.
Cotton and other annual crops operate differently. Major expenses occur around planting and throughout the growing season, followed by harvesting and marketing costs before the entire production cycle is financially complete.
Production budgets should therefore include more than basic inputs. Fuel, fertilizer, crop protection, irrigation, labor, machinery expenses, insurance, harvesting, transportation, repairs, and financing costs can all influence profitability.
Agricultural expansion adds another layer of complexity. More acreage or production capacity often requires additional machinery, employees, buildings, storage, transportation, water, and working capital.
Farm owners should identify those secondary expenses before committing to growth. Expanding production without expanding supporting infrastructure can create bottlenecks that reduce the anticipated financial benefit.
Machinery storage is one example. Larger tractors, sprayers, planters, harvesters, and implements can eventually outgrow existing facilities.
A well-designed agricultural equipment building can protect machinery and provide room for maintenance, organization, and secure storage. However, construction should be based on practical requirements rather than simply constructing the largest facility available.
Complete construction estimates matter. Site preparation, foundations, concrete, doors, electrical work, lighting, drainage, ventilation, access roads, and other improvements can materially increase final project costs beyond an advertised building package.
Seasonal crop inputs should be treated differently from permanent structures. Planting expenses normally generate value within a production cycle, while a building can remain useful for decades.
Using an excessively long repayment period for short-lived operating expenses can create financial problems because the farm may still be paying for previous production while funding the next season.
Farmers should maintain cash-flow forecasts showing when expenses occur and when revenue is expected. This makes it easier to anticipate periods of peak borrowing and evaluate whether available liquidity is sufficient.
Contingency reserves are also valuable. Weather, crop disease, equipment breakdowns, replanting, unexpected labor expenses, weaker yields, or changes in commodity prices can affect results.
Government agricultural programs may provide options for eligible producers. FSA administers direct and guaranteed programs that can address certain qualifying ownership and operating requirements.
Applicants should verify current rules directly rather than assuming a project qualifies. Eligibility depends on the producer, proposed use, financing program, repayment ability, and other requirements.
Farmers should also understand who they are dealing with when researching financing. Banks, agricultural credit institutions, government agencies, marketplaces, brokers, and affiliate websites can play different roles in the process.
Comparing rates is useful, but total cost matters more. Fees, repayment schedules, collateral, required equity, guarantees, and prepayment terms can materially affect a financing decision.
Agricultural businesses can improve future planning by comparing projected results with actual performance. Crop yields, planting costs, labor expenses, equipment utilization, construction expenses, operating margins, and debt payments can all provide useful information.
Those records can feed into a multi-year capital plan that anticipates future land improvements, machinery replacement, building construction, irrigation upgrades, storage requirements, and working-capital needs.
Growth should ultimately be based on productive capacity and financial strength rather than simply on the availability of additional borrowing.
No agricultural financing product is automatically approved. Available amounts, interest rates, fees, repayment schedules, collateral requirements, required contributions, guarantees, and eligibility depend on the provider, program, applicant, and transaction.
A disciplined financing strategy combines complete budgets, conservative assumptions, adequate liquidity, appropriate repayment periods, and ongoing performance measurement. That approach can help agricultural businesses expand while maintaining the financial flexibility needed to handle the uncertainties inherent in farming.